The state of social media in 2026: Data from Sprout’s latest pulse survey

Written by Benedict Nicholson
Published on September 23, 2026
Reading time 5 minutes
Table of Contents
Social media never holds still, and neither do the people using it. To see where things stand heading into the end of 2026, we surveyed 2,250 consumers from August 11 to August 18, 2026 for Sprout’s Q3 Pulse Survey, which provides a regular check-in on how consumer behavior and expectations shift in real time.
This version turned up some clear signals: shoppers are starting earlier and watching prices more closely, customer service is happening more than ever on social networks, we might be heading for the first real vertical video election cycle and audiences are getting pickier about what counts as on-brand versus just noise.
Here’s what the data says, and what it means for your strategy through the rest of the year.
Holiday shopping is likely to happen earlier
Much like the trees that populate the season, the debate on when to launch holiday campaigns is evergreen. But brands worried about campaigns beginning too soon can put that fear to rest. While half of consumers (50%) still see October and November as the ideal window for holiday campaigns, most won’t let this affect their actual buying behavior. Nearly half of consumers (49%) say they’re more likely to buy from a company that starts campaigns as early as August, and another 40% say early launches make no difference either way. Only 11% say it turns them off.
Economic pressure is driving much of this behavior, as tariffs impact consumer spending. More than a third of consumers (36%) say they’re shopping earlier specifically to get ahead of tariff-related price increases, and another 27% are worried about price hikes even if they’re not sure it’s changed their timeline. That’s 63% of consumers whose holiday plans are shaped by inflation and tariff concerns, Gen Z (48%) and millennials (41%) most of all.
Brands that lead with value messaging and early-bird pricing stand to win here, and that point is illustrated by what consumers say they want from holiday social campaigns. The top response for what will make them most likely to buy from companies was promo codes shared by brands or influencers (30%), showing that customers’ nose for a deal is going to be the key deciding factor when it comes to holiday purchases.
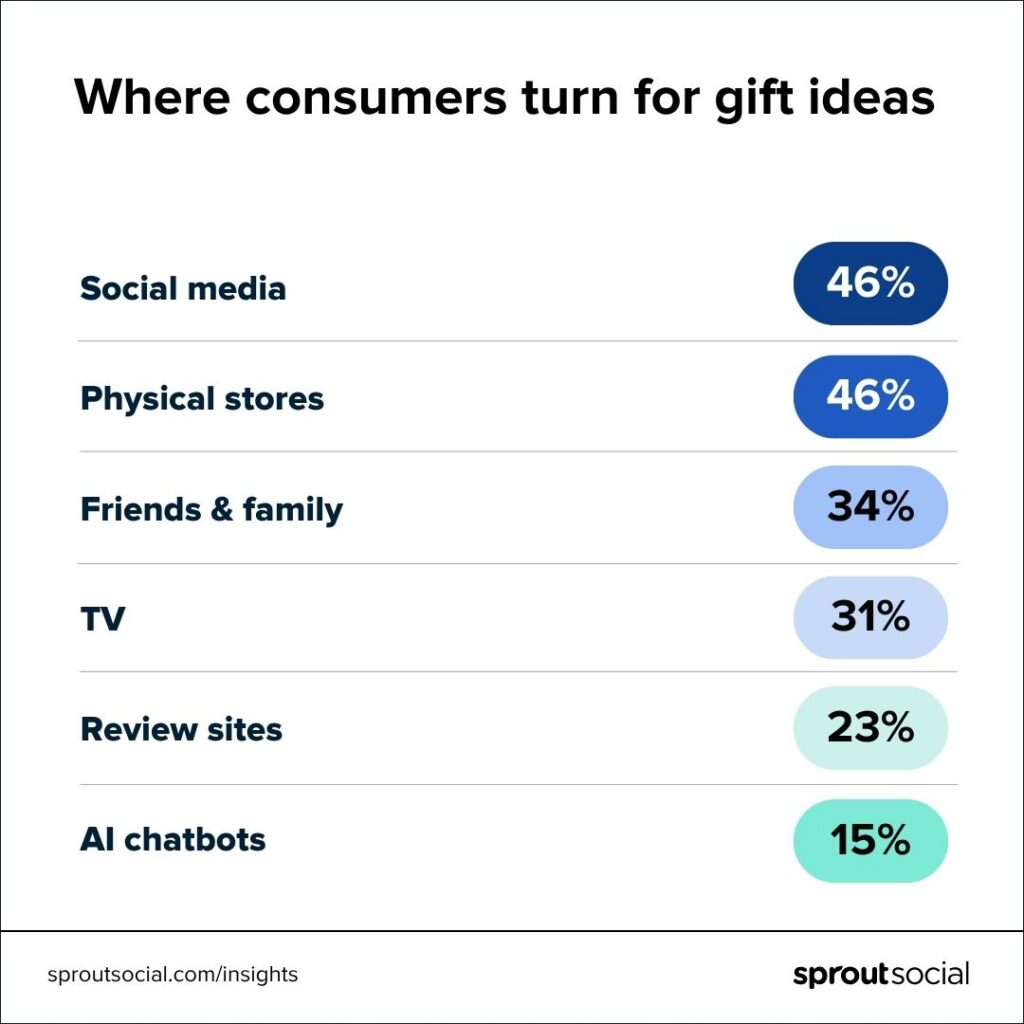
And it’s on social that they’ll discover the deals. Physical stores and social media are tied at 46% each as the top source for gift inspiration, with recommendations from friends and family close behind at 34%. Social’s pull skews young, with 54% of Gen Z and 50% of millennials turning to it for gift ideas, versus just 31% of boomers, who still lean hard on physical stores (53%).
Social will be a key landscape for pre-purchase consideration, but it will also play a role in what happens after money is exchanged.
Brands should expect more customer service inquiries on social
Compared to last year’s holiday season, 27% of consumers plan to use social media more for customer service questions, and another 59% expect to use it about the same amount as before. Social isn’t going anywhere as a support channel. If anything, it’s growing.
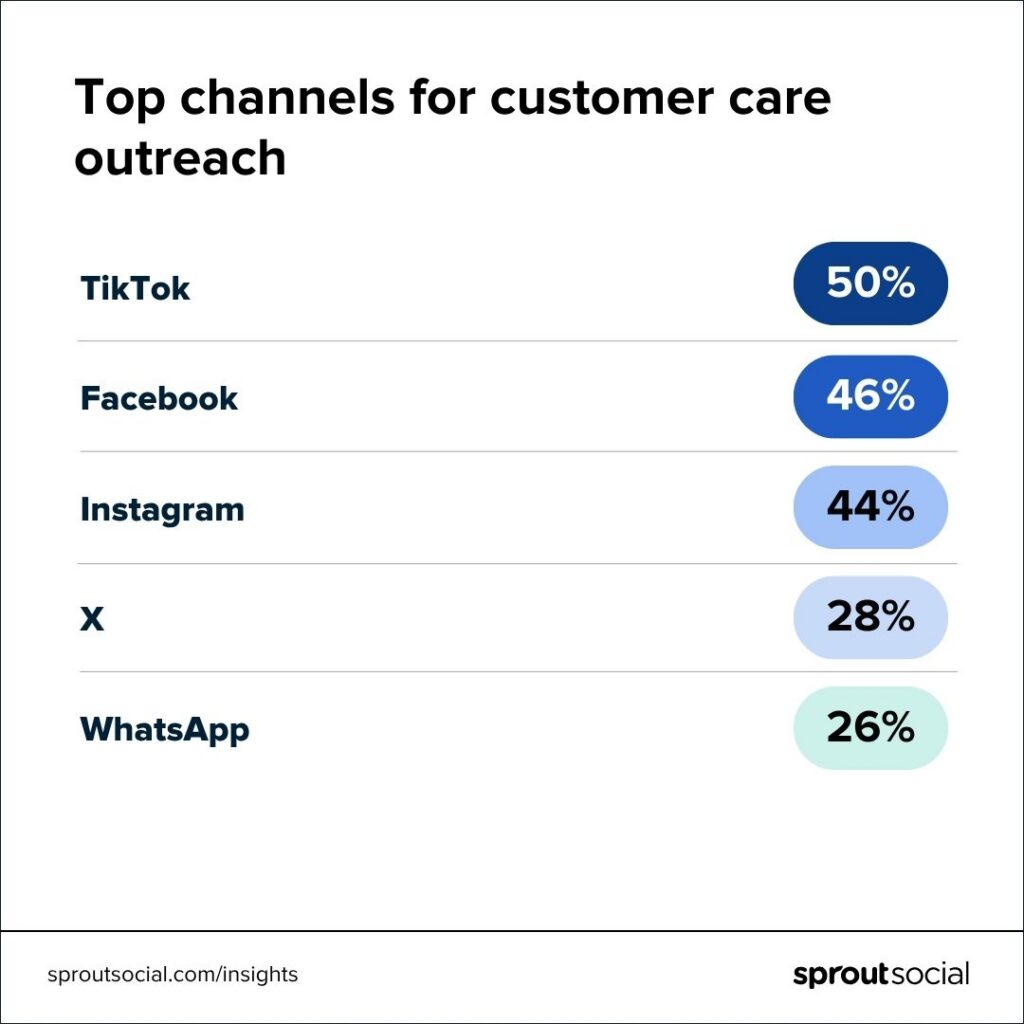
TikTok (50%) and Facebook (46%) lead as the platforms consumers turn to first for customer service, followed closely by Instagram (44%), then X (28%) and WhatsApp (26%). Brands need coverage across more than just their biggest channel.
Most consumers (55%) would rather slide into a company’s DMs than air a complaint publicly, though 31% will leave a comment on a post and 13% will tag the brand directly. When people do go public, expectations split almost evenly: 33% want a reply directing them to DM for resolution, while 28% expect the issue solved right there in the comments. Either approach works, as long as it’s consistent.
Speed is non-negotiable in this exchange. Most consumers (68%) expect a response within 24 hours, but a meaningful chunk wants it faster: 24% expect a reply in 1-2 hours, and 14% expect one in under an hour. Brands should set social care SLAs with these windows in mind, not general email-support timelines.
Consumers are also broadly comfortable with AI chatbots handling first-line questions.
Social media will play a big part in the midterms
Traditional news is still the main source of political information heading into the midterms, but social is closing the gap fast. Among U.S. consumers, 38% say they’ll rely on TV news for election coverage, 30% will turn to social platforms and 28% will lean on news websites and apps.
For now, TV holds the top spot, but the gap is narrow enough that social platforms are shaping how people process what’s happening during election season. For younger generations, social dominates. Social media is the top source for both Gen Z (33%) and millennials (38%), ahead of TV and word of mouth.
Usage patterns will mostly hold steady through election season, and 44% of consumers say their social media habits won’t change. But the rest are actively managing their exposure. Over a quarter (26%) plan to spend less time on social to avoid political content altogether, and 24% say they’ll mute or unfollow accounts that get too political. For brands, that’s a signal to read the room: leaning too hard into political commentary risks getting filtered out entirely by a meaningful chunk of your audience.
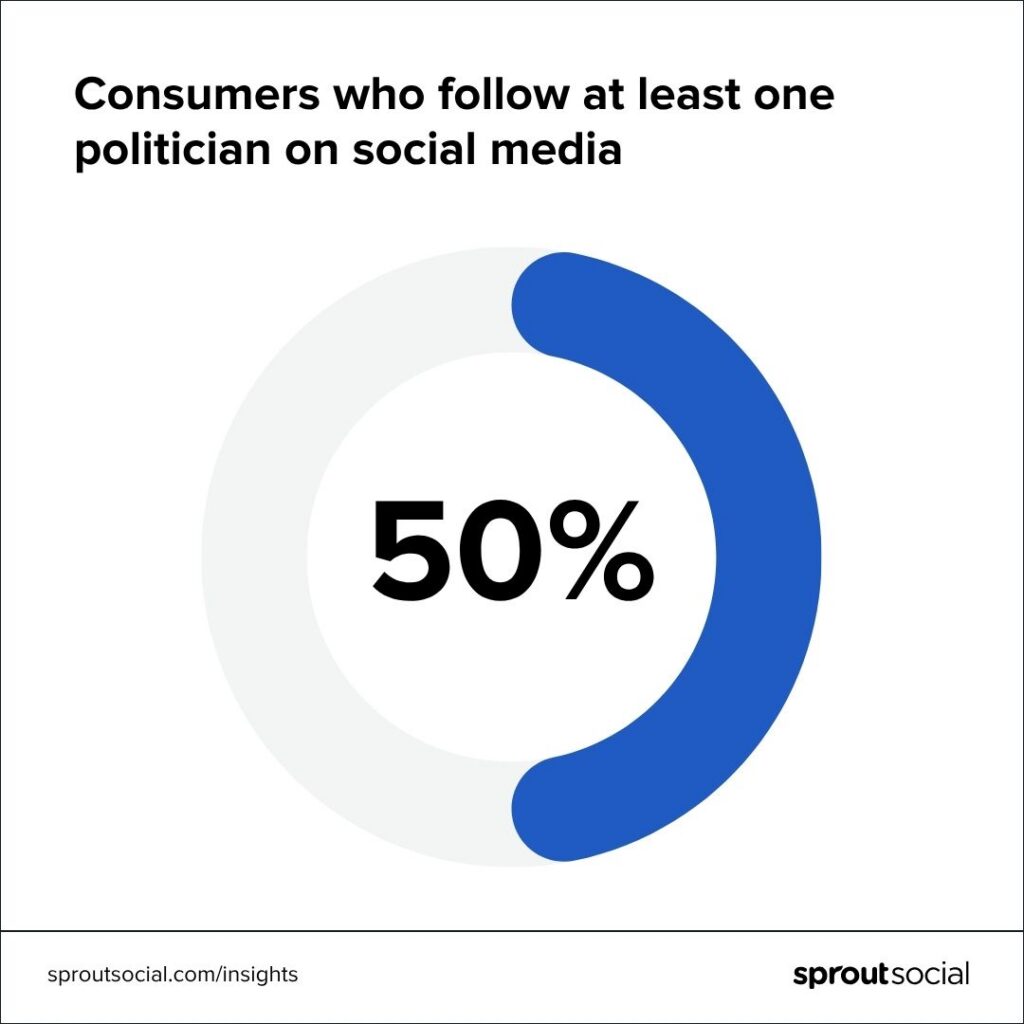
When it comes to political messaging, consumers report that politicians posting directly has a mixed effect, and the numbers suggest most people claim to be tuned out of it. A plurality of consumers (45%) don’t follow any politician on social, and 26% follow just one or two, so consumers aren’t seeking out politics deliberately. But among those who do engage, or who discover content through the algorithm, the impact is real: 33% say it makes politicians feel more approachable, and 55% say a post has changed or informed their opinion on something.
As for how brands themselves should behave in the lead up to elections, consumers aren’t handing out a clear playbook. 27% have no preference, and 23% think it should be business as usual. The rest are scattered across a range of approaches, with no single stance winning a majority.
AI causes wariness among voters
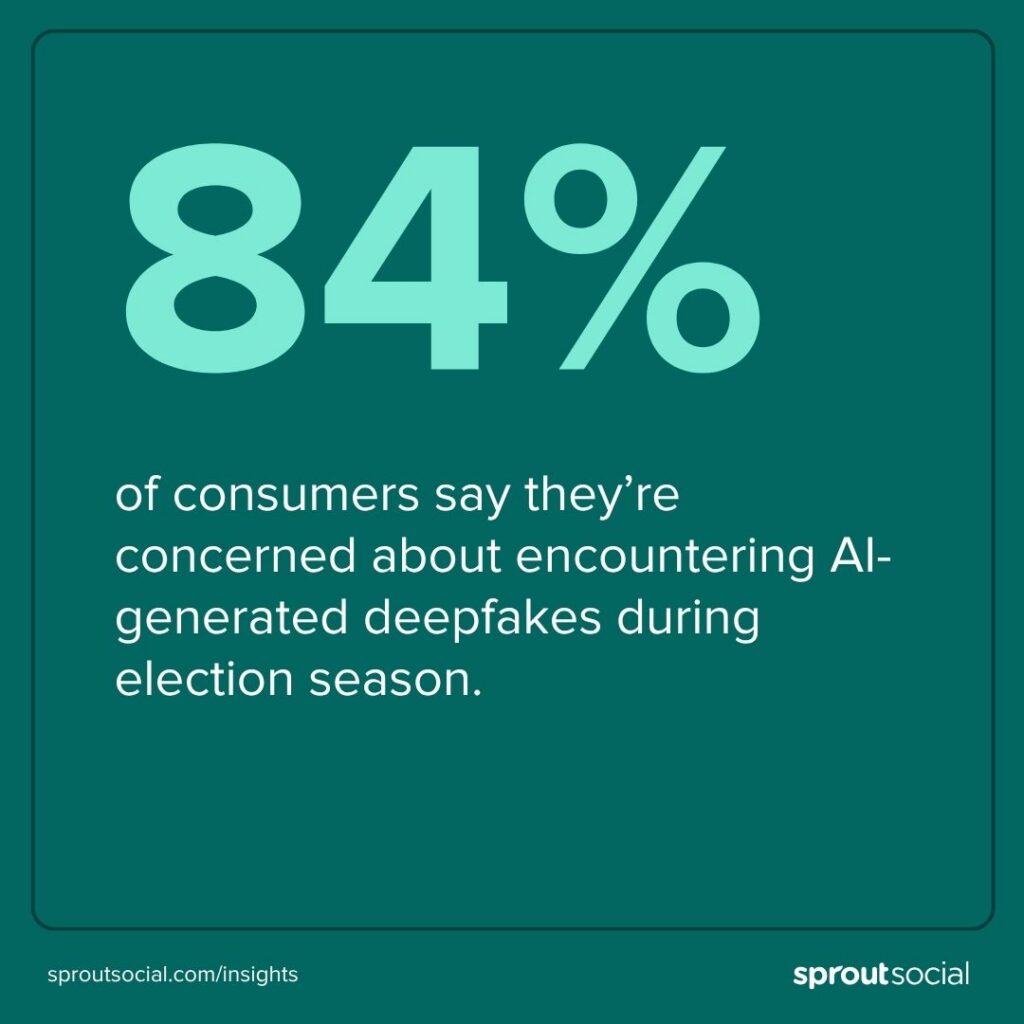
When you layer AI-driven distrust on top of all this, and the picture gets even more complicated. The vast majority of consumers (84%) say they’re concerned about running into AI-generated deepfakes, and 38% say that concern is making them more skeptical of ads in general — not just political content.
Any social team running AI-generated or AI-assisted creative during this window should expect a more skeptical audience by default, and lean harder into transparency: clear disclosure when AI is involved, and a bias toward content that’s obviously, verifiably real when the message actually matters. That’s good advice for brands too, even outside of the electoral window.
Consumers want brands to be more original
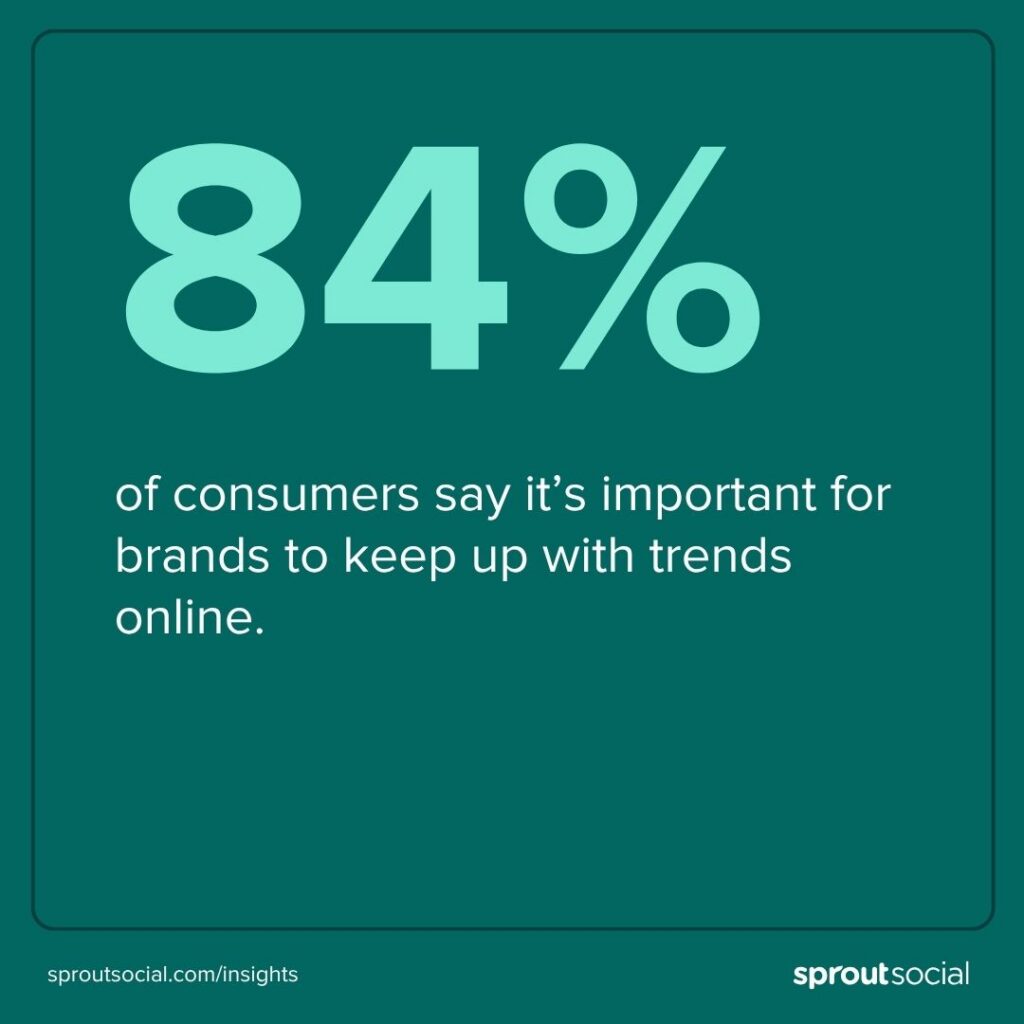
Social media has become the default place people go to keep up with trends and cultural moments, ahead of TV, streaming and even conversations with friends and family. And for the most part, brands are meeting the moment: 85% of consumers agree that most companies do a good job keeping their social content culturally relevant, and almost the same share (84%) say it’s important that they do.
But keeping up isn’t the same as being memorable. When every brand is jumping on the same trending sound or meme format, just participating in culture isn’t enough to build a real connection with an audience. It makes you blend in rather than stand out.
That distinction shows up most obviously in what actually drives loyalty. Quality of product or service still comes first, cited by 44% of consumers as their top priority. But originality of content is close behind at 33%, ahead of price, customer service and other traditional loyalty drivers. Once the product delivers, distinctive content is the strongest lever brands have left to pull.
But what does original mean in practice? It means dropping the corporate voice and not sounding the same as everyone else. Half of consumers (50%, combined) say they want brands to stop sounding salesy and corporate and start sounding authentic and relatable instead. Having a genuine, consistent voice underneath the trends is what makes brands stand out.
Want insight into the latest content trends? Read Sprout’s 2026 Social Media Content Strategy Report.

Share